Mobile game IAPs down 7% as no new releases break top-grossing charts this year

| Date | Type | Companies Involved | Key Datapoint |
|---|---|---|---|
| Oct 12, 2026 | report | Aream & Co | $19.6 billion |
- Mobile game in-app purchases fell to $19.6 billion in Q3 2026.
- There has yet to be a 2026 launch that has broken into the top-grossing chart.
Mobile game in-app purchases fell to $19.6 billion in the third quarter of 2026, down 7% year-over-year.
That’s according to Aream & Co’s Q3 2026 Video Game Market Update report, which also identified a 12% fall in console games revenue at its "steepest drop in two years". Nintendo saw the sharpest decline of the three major consoles, down 18% Y/Y more than a year on from the launch of the Switch 2.
Meanwhile, consumer spending on Steam helped sustain double-digit growth for PC games.
The report noted that mobile’s decline came with a smaller install base and a 10% drop in downloads, but publishers in Asia and Turkiye have continued to see a growing share. Most companies saw revenue growth, with Asian mobile-first companies up 11% overall and Western mobile-first companies up 6% Y/Y.
In the US, Niantic was the top-growing publisher quarter-over-quarter with $66 million in incremental in-app purchase revenue in the country. Roblox ranked second at $55m while Leiting Games ranked third at $16m.
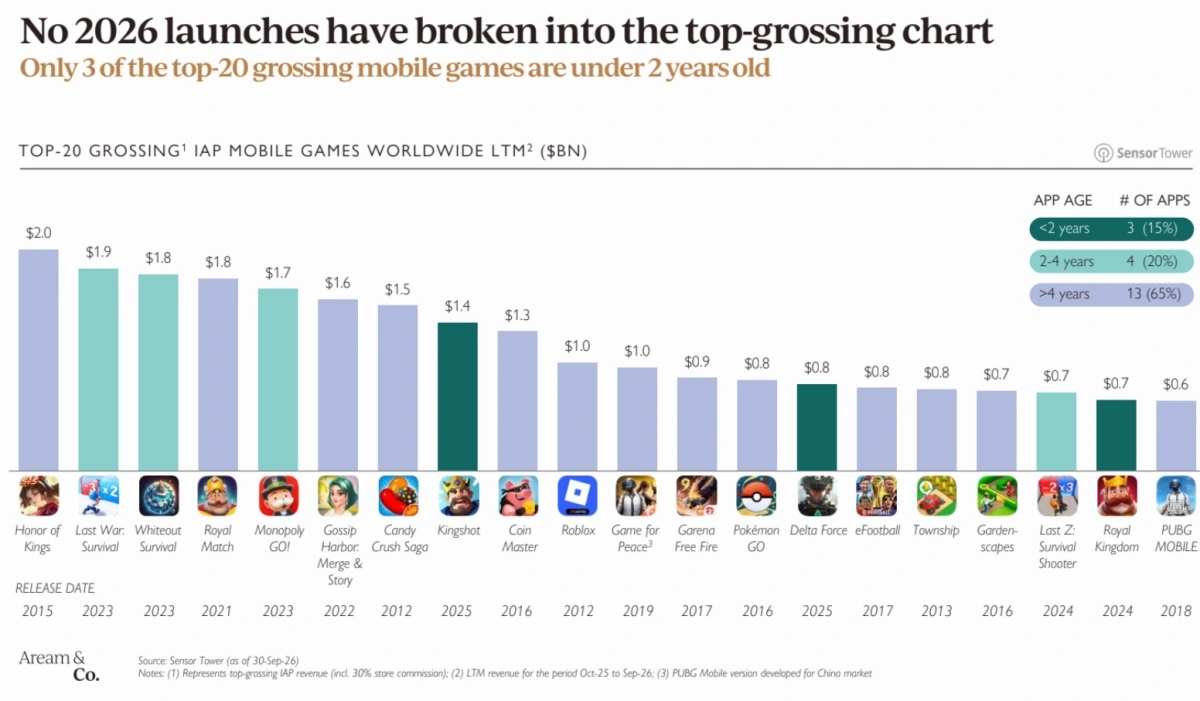
There has yet to be a 2026 mobile launch that has broken into the top-grossing chart globally, with Kingshot and Delta Force among the only top 20 games that are less than two years old.
Deals during Q3
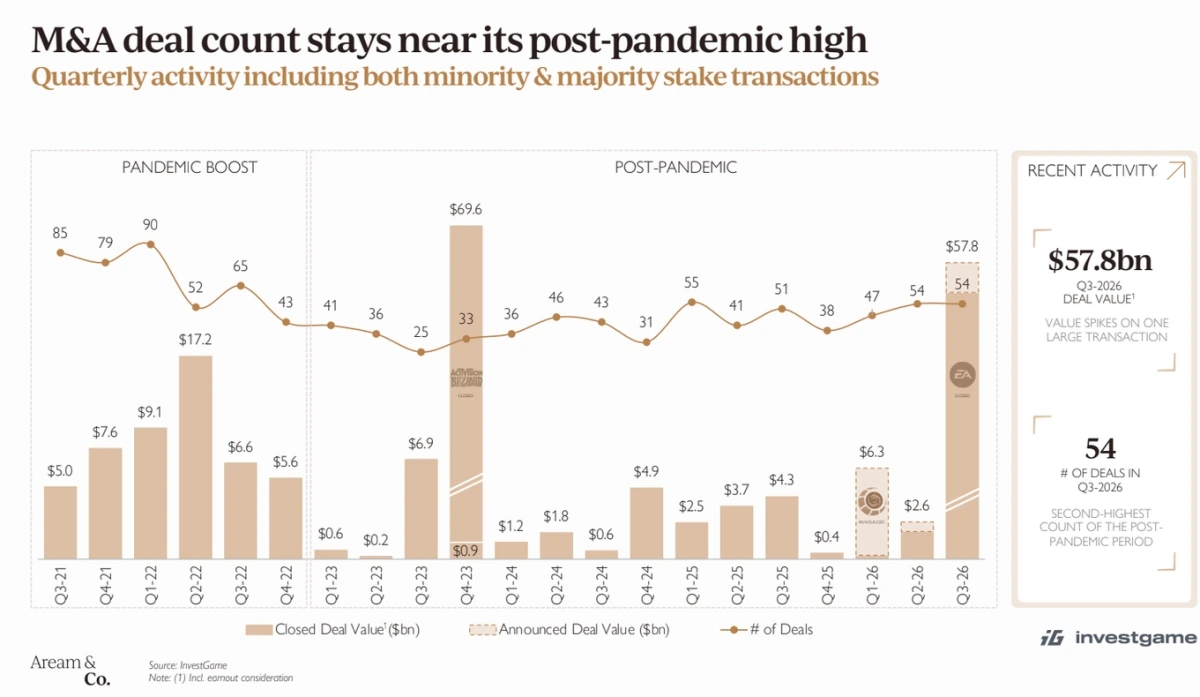
Aream & Co’s report also looked at M&A activity during the quarter. It found that Asian companies were behind most of the notable deals during Q3, while overall M&A deal count came close to a post-pandemic peak, at 54 total transactions.
Deals collectively saw $57.8bn deployed, predominantly a result of the $55bn deal to take EA private. Other acquisitions included Nazara’s purchase of Bluetile for $303m and Tripledot’s purchase of Supersonic for $40m, both completed in August.
Private investment more than tripled to $2.8bn across 137 deals, with late-stage rounds hitting $2bn, their highest since Q4 of 2021. Public offerings reached $1.3bn, up 122% Y/Y.
Among the deals this quarter, 18 were control deals for developers and publishers valued above $100 million, bringing this year’s total almost equivalent to 2023 to 2025 combined.
The full report can be found here.
Companies
